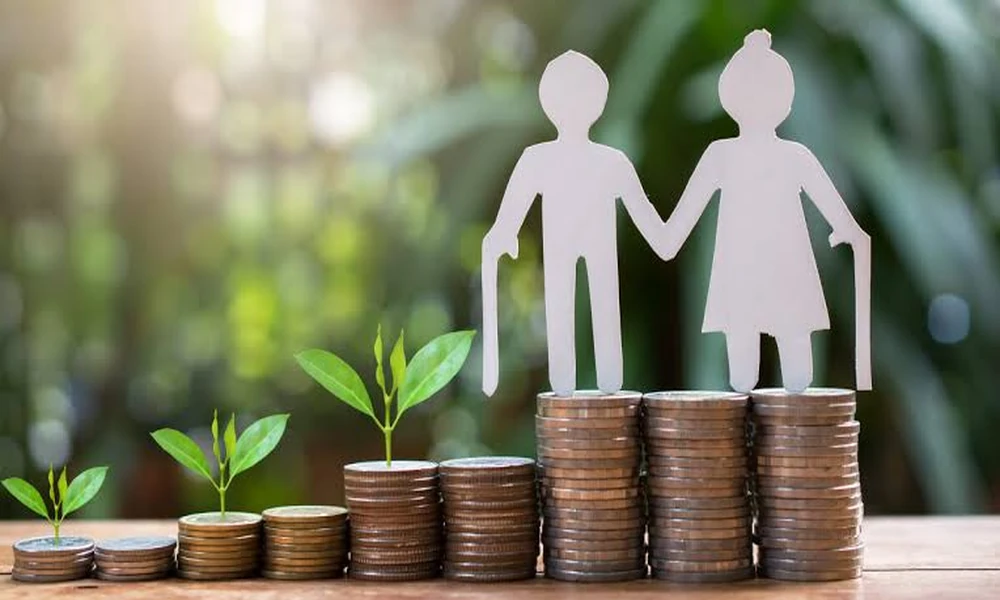

Retirement worry rarely stems from thin savings alone. Timing creates the sharper discomfort. A healthy CPF balance reveals little about arrival dates. For retirement planning singapore provides a dependable anchor in CPF LIFE. Around that fixed point, other income sources can be scheduled. Payout age, deferral, bridge funds and inflation shape that schedule.
Payout Age Anchors Every Income Timeline
CPF LIFE monthly payouts can begin at 65. That date stays put while employment rules shift. In July 2026, the statutory retirement age moved to 64. Re-employment eligibility climbed to 69 alongside it. Neither move alters when those payouts start. So a worker stopping at 64 waits one year.
What Does the Retirement Account Lock In?
At 55, a Retirement Account forms, setting lifelong income levels. For the 2026 cohort, the benchmarks run as follows:
- A Basic Retirement Sum of $110,200 delivers about $950.
- The Full sum of $220,400 brings roughly $1,780 monthly.
- An Enhanced sum of $440,800 pushes payouts near $3,440.
- Smaller balances still pay out, scaled to savings.
Deferring Payouts Buys Bigger Monthly Cheques
Every deferred year past 65 lifts payouts up to 7%. Starting at 70 turns $1,780 into about $2,380. That trade suits people still earning salaries. Through retirement planning singapore couples can stagger start ages. One spouse claims at 65; the other waits. The deferred payout grows larger, cushioning later decades.
Who Covers the Gap Before 65?
Leaving work at 60 or 62 opens a bridge period. Before CPF LIFE begins, other sources must carry spending:
- Part-time consulting keeps cash flowing.
- Dividend stocks deliver regular distributions.
- Rental units cover recurring bills.
- SRS withdrawals attract lighter tax.
- Fixed deposits mature on chosen dates.
Healthcare Costs Deserve Their Own Timeline
Medical bills seldom arrive on a predictable schedule. Below 65, the 2026 Basic Healthcare Sum stands at $79,000. Once MediSave hits that cap, extra contributions flow toward retirement. MediShield Life premiums, though, climb with age. A separate cash reserve stops hospital stays from raiding monthly payouts.
Can an HDB Flat Fund Monthly Income?
Through the Lease Buyback Scheme, seniors keep living at home. Owners aged 65 or older sell the lease’s tail end. Proceeds top up the Retirement Account, then buy CPF LIFE. Smaller 3-room flats earn bonuses up to $30,000. Bricks, in effect, become a monthly paycheque.
Will Inflation Erode a Fixed Payout?
CPF LIFE answers this risk with an Escalating Plan. Payouts open lower, then rise 2% each year. A $1,000 starting amount reaches about $1,500 by 85. The Standard Plan, by contrast, stays level throughout. Health, family longevity and other assets should guide that choice.
The Twelve Months Before CPF LIFE
Under the 2026 rules, retirement can arrive at 64. CPF LIFE, however, opens its tap at 65. Priced at $1,780 a month, that gap exceeds $21,000. Few household plans name the figure outright. Retirement is less one date than a chain of handovers. Each handover needs a funded bridge, measured in months.
FAQs
Can CPF LIFE payouts begin before age 65?
No, 65 is the earliest start under current rules. Members may defer up to 70 for higher monthly amounts.
Does topping up beyond the Full Retirement Sum earn tax relief?
Relief covers cash top-ups only up to the current Full Retirement Sum. Amounts above that raise payouts without lowering tax bills.
What if Retirement Account savings fall below the Basic sum?
Payouts still arrive, sized to the available balance. Members outside CPF LIFE receive at least $350 monthly until savings run out.
Should both spouses start payouts at the same age?
Not necessarily, since staggered starts can smooth household income. One payout covers early years while the other grows through deferral.
Unsure About Future Cash Flow? Retirement Planning Creates Clear Income Timelines

How Vehicle Age Affects Car & Motorcycle Insurance
Don’t Get Towards The Disillusion of Holiday Insurance Policy